
Medicare Part D Notices Are Due By October 15
The date for distributing Medicare Part D notices is approaching.

For employers with multiple related companies, understanding how the ACA treats employees who move between entities is important for accurate eligibility and reporting.
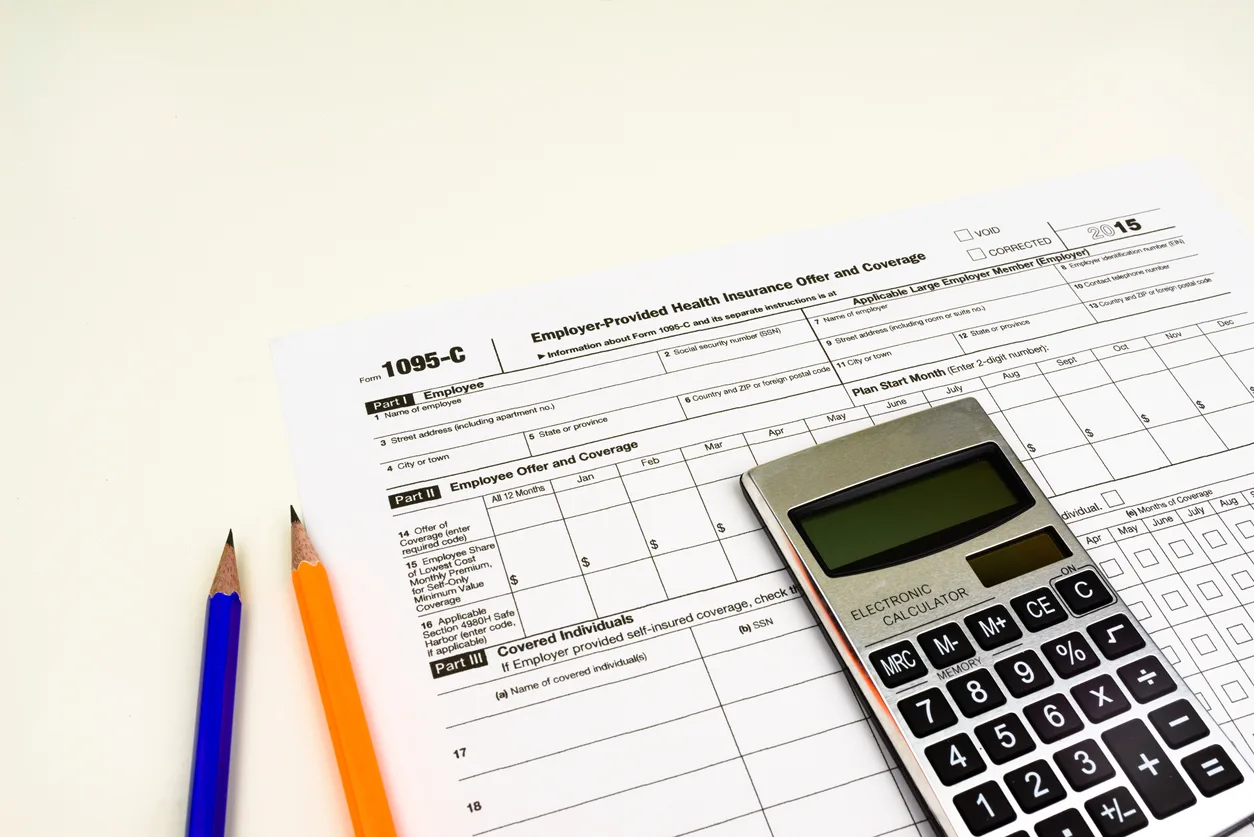
Organizations with multiple related companies often share employees, benefit plans, HR departments, payroll systems, and administrative processes. From an HR perspective, moving an employee from one related company to another may feel like a simple internal transfer. Under the Affordable Care Act (ACA), however, the legal employer matters.
Under the ACA, certain companies with common ownership or other relationships are generally treated as a single employer when determining whether they are an Applicable Large Employer (ALE). These rules are commonly referred to as the controlled-group or employer aggregation rules.
An employer is generally an ALE if it employed an average of at least 50 full-time employees, including full-time equivalent employees, during the preceding calendar year. When companies are required to be aggregated under the controlled-group rules, employees of the related companies are combined when determining whether that 50-employee threshold has been reached.
For example, assume Company A and Company B are members of the same controlled group. Company A has 40 full-time employees and Company B has 25. Although neither company has 50 full-time employees on its own, the companies may collectively constitute an ALE because their employees are combined for purposes of determining ALE status.
Once the group qualifies as an ALE, each separate employer within the group is generally considered an ALE Member and has its own ACA responsibilities.
This distinction is important. Related companies may be combined to determine whether they are subject to the ACA employer mandate, but that does not mean they file one combined set of ACA forms.
Each ALE Member generally files Forms 1094-C and 1095-C using its own Employer Identification Number (EIN) and reports information about its own full-time employees.
As a result, an employee who moves between two related companies during the year may need to receive a Form 1095-C from each company.
This is different from an employee who simply moves between departments, locations, or divisions of the same legal employer. If the employee remains employed by the same ALE Member under the same EIN, the employer generally reports the employee on one Form 1095-C.
Consider an employee who works for Company A from January through June and transfers to related Company B effective July 1.
Assuming both companies are separate ALE Members, Company A generally reports the employee for the months for which Company A is treated as the employee’s employer, while Company B reports the employee for the applicable months following the transfer.
Employers should therefore be careful about treating transfers between related entities as ordinary internal transfers. The employee may remain within the same overall corporate organization and even the same benefit plan, but the change in legal employer can affect ACA reporting.
The situation can become more complicated when the employee has hours of service for both companies during the same calendar month.
Under the ACA rules, if an employee works for more than one ALE Member within the same controlled group during a month, the employee is generally treated as the employee of the ALE Member for which the employee had the greatest number of hours of service during that month.
For example, suppose an employee transfers from Company A to Company B during July. During July, the employee has 40 hours of service with Company A and 120 hours with Company B. For ACA purposes, Company B would generally be treated as the employee’s employer for July.
If the employee has an equal number of hours for two ALE Members during the month, the employers must treat one of the ALE Members as the employer for that month.
This means the effective date of a transfer alone may not determine which company is responsible for ACA reporting for the transfer month.
Employers should also be careful about treating an employee who transfers between members of a controlled group as a completely new employee for ACA purposes.
When an employee works for multiple employers that are part of the same Aggregated ALE Group, the employee’s hours of service for the related employers generally are combined when determining the employee’s total hours of service.
This can be particularly important when an employer uses the look-back measurement method to determine full-time status. Moving an employee from one related company to another does not necessarily mean the employee’s ACA measurement history starts over.
Transfers between related companies can create ACA problems when different systems do not communicate with one another. For example, one company’s payroll system may show a termination while the other shows a new hire, even though the employee has continuously worked within the same controlled group.
Employers with multiple related entities should have procedures for identifying these transfers and communicating them to the people or vendors responsible for ACA administration. Particular attention should be given to the employee’s legal employer, EIN, transfer date, hours of service, measurement and stability period information, offers of coverage, and employee contribution information.
A transfer from one department to another is not necessarily the same as a transfer from one legal employer to another.
Employers with multiple related entities should understand which companies are members of their controlled group and which EIN employs each employee. When an employee moves between those entities, HR should consider the ACA implications before simply terminating the employee under one company and processing the individual as an entirely new employee under another.
A little coordination at the time of the transfer can prevent much more difficult eligibility and ACA reporting problems at year-end.
Benefit Allocation Systems (BAS) provides online solutions for: Employee Benefits Enrollment; COBRA; Flexible Spending Accounts (FSAs); Health Reimbursement Accounts (HRAs); Leave of Absence Premium Billing (LOA); Affordable Care Act Record Keeping, Compliance & IRS Reporting (ACA); Group Insurance Premium Billing; Property & Casualty Premium Billing; and Payroll Integration.
MyEnroll360 integrates with major insurance carriers for enrollment eligibility management (e.g., Blue Cross, Blue Shield, Aetna, United Health Care, Kaiser, CIGNA and others), and with leading payroll platforms for enrollment deduction management (e.g., Workday, ADP, Paylocity, PayCor, UKG, and others).
This article is for informational purposes only and is not intended as legal, tax, or benefits advice. Readers should not rely on this information for taking (or not taking) any action relating to employment, compliance, or benefits. Always consult with a qualified professional before making decisions based on this content.
The date for distributing Medicare Part D notices is approaching.
Employers should avoid making eligibility decisions based solely on the employee's relationship to the individual.
Should health coverage end when an employee who has been working full-time moves to a part-time schedule?